 MCV/DEVELOP News, events, research and jobs from the games industry
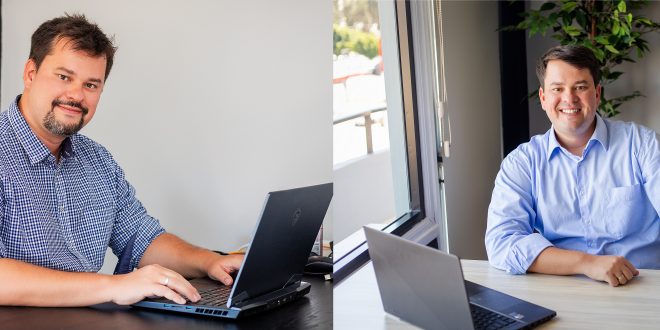
By Kirill and Roman Gurskiy at GEM Capital

Gamescom 2026 landed at an odd moment for the industry; money is starting to move again, and the industry’s biggest bet in years is about to decide who benefits from it. Behind the demos, the market itself was quietly changing shape.
GEM Capital spent the week watching that shift. Here, the Gurskiy brothers break down five takeaways on where the industry is headed.
Investors Are Gambling on Indies
The investment market in gaming is picking back up. New players are entering, and some investors who were active before a quiet stretch are now talking openly about getting back to dealmaking. But the capital returning to the table isn’t returning to the same assumptions it left behind. It’s coming back with a much harder read on where the actual odds of a hit sit, and that read starts with indie.
More of each year’s breakout titles are turning out to be indie games rather than AAA, made at a fraction of the budget and without a proportional drop in the odds of landing a hit. Investors are now doing that arithmetic openly and saying it out loud: many would rather put $10 million into ten indie games than $100 million into a single AAA title. Ten smaller bets, each with a real shot at breaking out, start to look statistically safer than one enormous bet that has to work.
That same logic is what’s driving the growing scepticism toward AAA development in the U.S. and Western Europe. The reasoning is simple. AAA development is expensive, and recent AAA hits haven’t kept pace with what they cost to make. A big budget used to be an argument on its own, a signal of seriousness and production value that investors could point to. That’s no longer enough. Investors have stopped asking how much a studio spent and started asking what the studio actually got for that spend: what shipped, how it performed, and whether the numbers justify the outlay.
That shift is opening up real space for studios building not the most expensive game on the market, but the sharpest one. For indie developers, that’s not a threat from bigger, better-funded competitors. It’s an opportunity, because the market is finally pricing craft and results over scale alone.
Mobile Is Down, But Not Out
Gamescom’s B2C side set an attendance record this year. But on the B2B floor, mobile has all but disappeared: the show’s tilted hard toward PC and console, and the mobile crowd that used to be there has thinned out. We think that tracks with where the segment actually stands today: the market’s tough, and it’s polarising – the rich get richer and the poor get poorer. New players may still show up, but the real driver is the cost of acquiring a user.
Budgets for developing a high-quality pc/console game and a mobile game became surprisingly close. Five to ten million dollars is enough to make a good indie PC or console game, land a solid publishing deal, and sell it well. Put the same five million into mobile and then you need another fifteen million just for marketing.
Investors haven’t walked away from mobile, though: they’ve gotten narrower about where they look. Turkey and Vietnam are the two hubs getting the attention, and Turkey is the trickier of the two. Heavy investor interest has pushed early-stage valuations up, in some cases several times higher than comparable startups elsewhere in Europe or Asia.
Later-stage, valuations track the same financials everywhere: EBITDA, free cash flow, and revenue put a company in roughly the same range regardless of geography. It’s only at the early stage that Turkey gets expensive, because investors are pricing in above-average odds that these startups become the next big thing. That premium only pays off if enough of them actually do.
The focus on casual specifically isn’t arbitrary either. Turkey’s breakout successes – Dream Games, Peak Games – are casual studios, and most new Turkish startups are founded by their alumni, building on what already worked.
Financials Are King
For M&A in gaming, financial performance comes first. EBITDA and free cash flow sit above everything else on the checklist, and that priority itself isn’t new. What has changed is how carefully buyers now check the math behind those numbers, and how much further down the list they’re willing to look before writing a check.
A few years ago, a strong trailer, a loud community, and a single breakout title were often enough to carry a deal. Wishlist counts, Discord numbers, and press coverage worked as stand-ins for future revenue, and a buyer could reasonably bet that a studio with one hit would find a way to produce a second. Founder-reported numbers were largely taken at face value, and a studio living off one game’s revenue wasn’t automatically a red flag; it was just how most studios looked.
That’s no longer enough on its own. Buyers now dig into whether revenue is repeatable or riding entirely on one title, because a studio that depends on a single hit is a studio one soft launch away from losing its entire business. They look at retention and lifetime value against user acquisition cost, not just top-line revenue, because a game that spends its way to a big number isn’t the same asset as one that earns it. They ask whether the team that made the hit is still there, since a studio’s most valuable asset can walk out the door before the deal closes. And they want audited financials, not founder math, because the gap between a compelling pitch deck and an accurate P&L is exactly where too many acquisitions used to go wrong.
Too many studios still think a great game is the pitch. It isn’t. A game studio has to function as a business, and a business has to make money on its own, not on the promise of a sequel or a live-ops roadmap that hasn’t shipped yet. The very best teams can still get acquired on craft alone, even without profitability behind them, that hasn’t disappeared. What’s changed is how rare and how visibly exceptional a team has to be to still get that pass.
VC Funds Are Changing How They Play
That same demand for provable financial performance is reshaping how funds themselves choose to invest. Many traditional gaming VCs have moved away from direct equity investment altogether. Instead, they’re funding specific, narrower bets: project financing for PC and console titles, and UA financing for mobile campaigns.
The appeal of this is straightforward. These deals are easier to evaluate and much faster to close than a traditional round. Classic early-stage equity means betting on a team first and then waiting years through successive funding rounds, a launch, and eventually a sale process that eats up plenty of time on its own, with no guarantee any of it pays off. Project financing works differently. It usually comes in as last-mile money to finish a game that already has real wishlist traction behind it, which lowers the risk considerably, and once the game ships, the fund collects a straight percentage of revenue instead of shopping around for an exit years down the line. UA financing is lower risk still. It functions closer to a lending product than a venture investment, and it goes to studios that have already proven they can scale and spend profitably, leaving little room for guesswork.
The tradeoff for all of this lower risk is reduced upside. A single equity hit can return an entire fund on its own, the kind of outcome that justifies years of patient, uncertain bets. Project and UA financing simply don’t work that way. Lower risk comes bundled with a hard ceiling on return, and funds increasingly must choose which of those two things they actually want.
Dreading and Betting on GTA
GTA 6 came up constantly. Everyone’s bracing for the release, set for November 19, 2026. Major publishers have shifted their own launches to September and October just to avoid landing in the same month as GTA 6. September 2026 is now overloaded with releases as a result.
At the same time, there’s real hope riding on it: the game’s budget, per analyst estimates, sits at $1–2 billion, which could make it the most expensive title ever made, and pre-orders — open since late June — are expected to beat GTA V’s record of 32.5 million copies sold in its first month.
If GTA VI breaks that record, the news will reach places gaming usually doesn’t — mainstream press, earnings calls, generalist investors who don’t normally look at the industry. They’ll see numbers that size and want a piece of it. That’s how outside capital enters a market. And once it’s in, funding follows for other projects too, not just Rockstar’s.
Now Pricing Results, Not Promises
The market is walking away from investing in stories and toward investing in proven numbers. Investors no longer pay for the scale of an ambition – they pay for how well a dollar converts into a player.